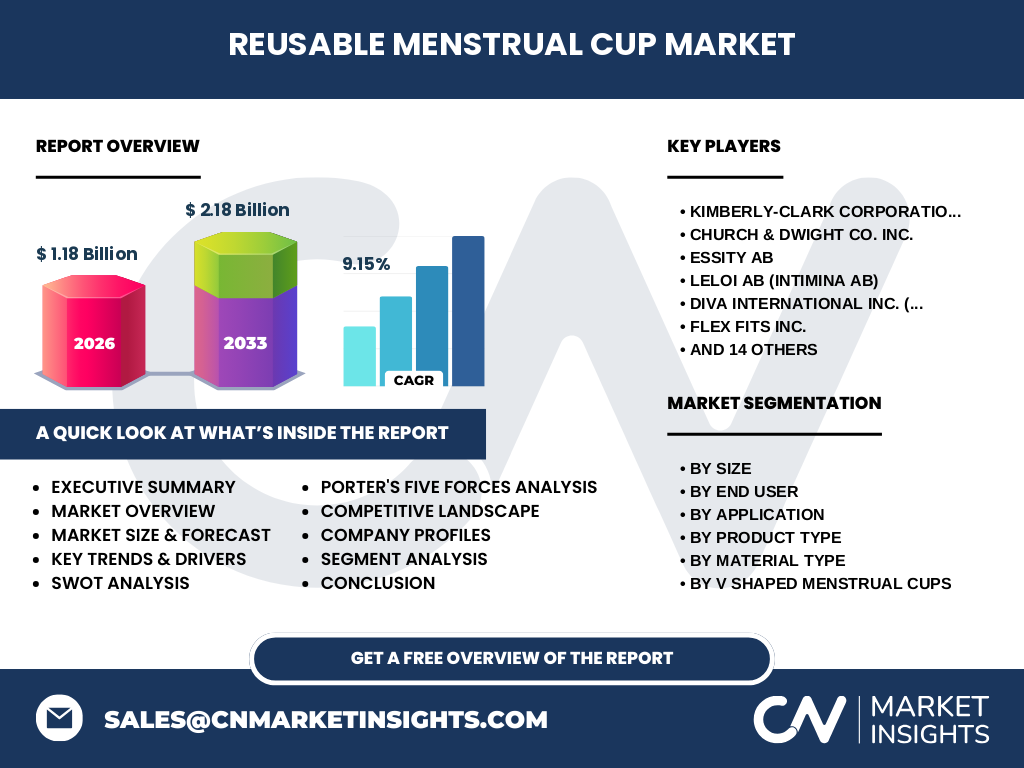
Market overview of the Reusable Menstrual Cup Market
Our analysis indicates that the Reusable Menstrual Cup Market stands at a valuation of $1.18 Billion in 2026. This sector encompasses medical-grade silicone, TPE, and natural rubber latex devices designed for sustainable menstrual hygiene management, driving profound shifts in global feminine care supply chains.
Structural Growth Drivers and Restraints
The Reusable Menstrual Cup Market industry trends reveal a strong 9.15% CAGR driven by eco-conscious consumer adoption. However, market restraints include cultural stigmas and regulatory hurdles enforced by agencies like the FDA, alongside complex supply chain logistics through major container ports.
The Shift Toward Sustainable Innovation
Emerging growth patterns within the Reusable Menstrual Cup Market highlight consumer migration toward Medical Grade Silicone Cups and Bell Shaped Menstrual Cups. Innovators are prioritizing hypoallergenic profiles and zero-waste packaging to capture expanding market share.
COVID-19 Impact Analysis on Supply and Demand
The pandemic severely disrupted global logistics networks for the Reusable Menstrual Cup Market, halting raw material shipments of medical-grade silicone. Post-COVID recovery trajectory demonstrates accelerated e-commerce penetration, as brands like Diva International Inc. and Saalt LLC optimized direct-to-consumer digital channels.
Competitive Benchmarking and Industry Concentration
Competitive dynamics in the Reusable Menstrual Cup Market feature a mix of agile disruptors and multinational giants. Kimberly-Clark Corporation and Essity AB compete alongside specialized players like AllMatters ApS, driving high market concentration via aggressive sustainability campaigns.
Executive Summary of Strategic Findings
Our research confirms that the Reusable Menstrual Cup Market will expand from $1.18 Billion in 2026 to $2.18 Billion by 2033. Strategic focus on adolescent and postpartum demographic segments remains vital for long-term category expansion and sustained profitability.
Market forecast from 2027 to 2033
Based on our econometric modeling, the Reusable Menstrual Cup Market is projected to surge to $2.18 Billion by 2033. This trajectory reflects a steady 9.15% CAGR, underpinned by rising disposable incomes and corporate menstrual equity programs.
Segmentation Analysis by Size and Material
The Reusable Menstrual Cup Market analysis segments demand across product architecture and composition. Key segments include:
- By Size: Small, Medium, and Large Size Cups
- By Material: Medical Grade Silicone, TPE, and Natural Rubber Latex Cups
- By Application: Menstrual Hygiene and Pain Management
Regional Market Distribution and Performance
Geographic evaluation of the Reusable Menstrual Cup Market highlights North America and Europe as dominant revenue generators. Meanwhile, Asia-Pacific exhibits the fastest adoption rate, propelled by government-backed menstrual health initiatives and expanding retail pharmacy distribution networks.
In-Depth Regional Review and Regulatory Landscapes
Regional performance within the Reusable Menstrual Cup Market is heavily shaped by regional compliance frameworks. European markets adhere strictly to stringent ISO and CE medical device certifications, favoring established players like Mooncup Ltd. and MeLuna GmbH.
Company Profiles and Strategic Positioning
Leading industry participants leverage distinct product portfolios within the Reusable Menstrual Cup Market. Brands like Hello Period Co., Lena Cup LLC, and Ruby Life Ltd. differentiate through ergonomic designs, social impact models, and multi-material offerings spanning TPE and silicone.
Porter's Five Forces Analysis of Competitive Intensity
The Reusable Menstrual Cup Market exhibits moderate-to-high rivalry due to low switching costs among consumers. However, supplier power remains moderate, constrained by specialized chemical manufacturers providing certified medical-grade silicone and thermoplastic elastomers.
SWOT Analysis of the Reusable Menstrual Cup Market
Our SWOT assessment identifies high gross margins and eco-friendly consumer alignment as primary strengths for the Reusable Menstrual Cup Market. Weaknesses involve initial consumer adoption barriers, while expansion into emerging economies represents a lucrative strategic opportunity.
Value Chain Analysis from Raw Materials to End-Users
The value chain for the Reusable Menstrual Cup Market begins with chemical synthesis of raw silicone and TPE polymers. Precision injection molding follows, culminating in distribution via specialized B2B medical distributors, digital marketplaces, and traditional retail pharmacies.
Investment Insights and High-Potential Areas
Investors targeting the Reusable Menstrual Cup Market should prioritize companies scaling Compact Round Shaped Menstrual Cups and digital health ecosystems. Strategic partnerships with gynecological health providers offer high-yield customer acquisition channels.
Conclusion and Strategic Takeaways
Ultimately, the Reusable Menstrual Cup Market represents a high-growth, sustainable pillar of modern feminine hygiene. Reaching $2.18 Billion by 2033 requires stakeholders to invest in consumer education, regulatory compliance, and versatile product lines tailored to diverse anatomical needs.
Research Methodology and Data Triangulation
Our baseline estimates for the Reusable Menstrual Cup Market are triangulated using a rigorous mix of trade registry data, primary stakeholder interviews with manufacturers like Ami Polymer Private Limited, and secondary macroeconomic indicators from global health organizations.
Scope of the Report and Coverage Parameters
This report on the Reusable Menstrual Cup Market covers global market dynamics from 2026 to 2033. Scope parameters include detailed breakdowns by material type, application, and end-user demographics, while excluding disposable sanitary protection categories.
Recent Developments and Industry Partnerships
Recent strategic moves in the Reusable Menstrual Cup Market include eco-certifications and distribution expansions by firms like Peptonic Medical AB and Cora. These initiatives aim to capture mainstream retail shelf space and validate clinical efficacy against traditional menstrual products.